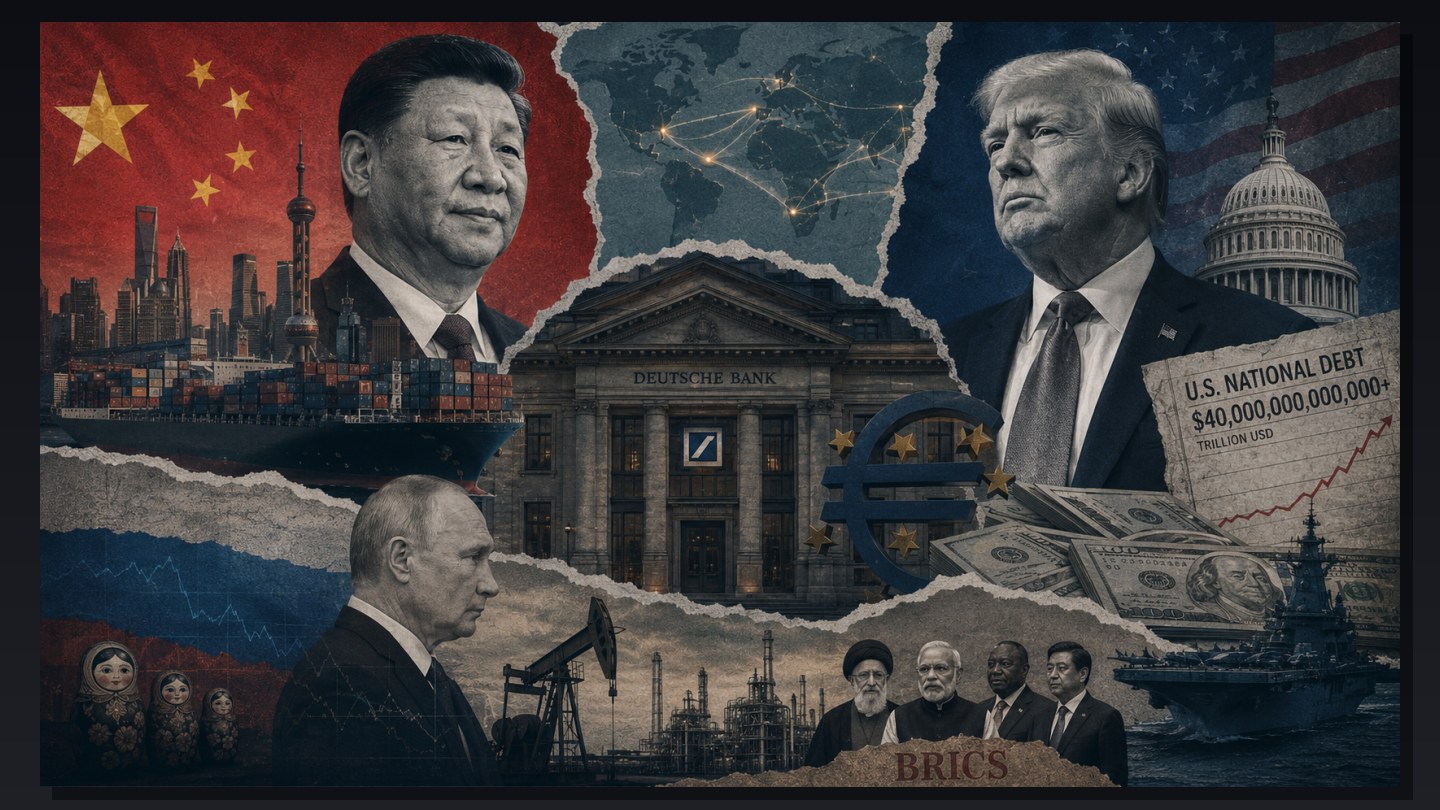
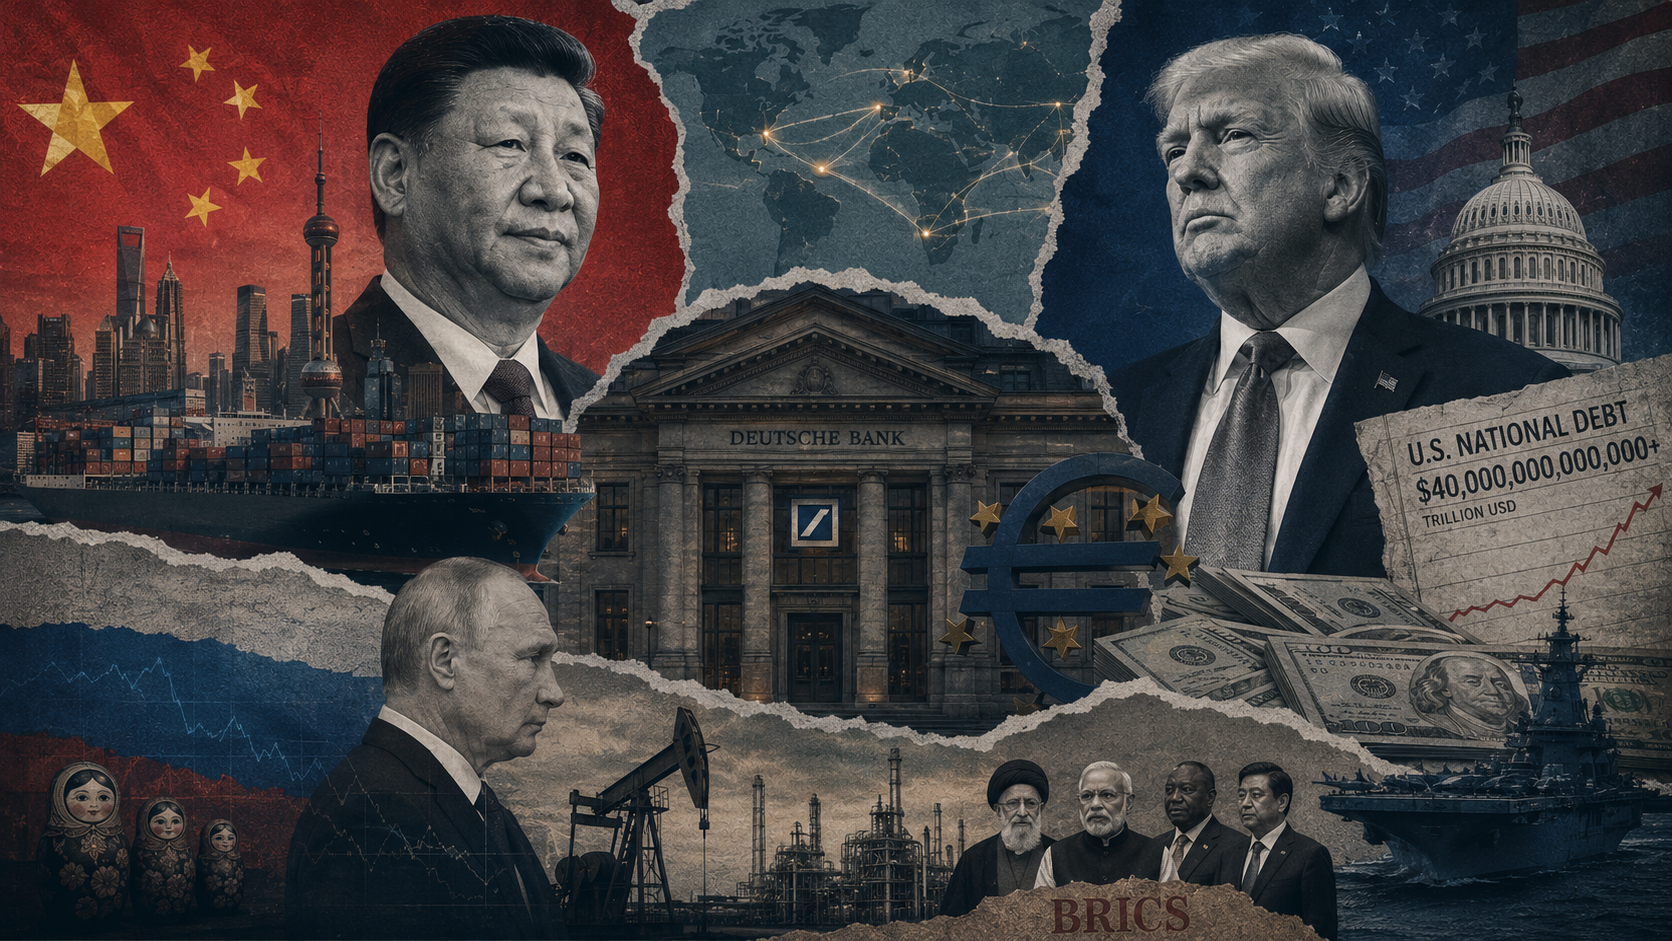
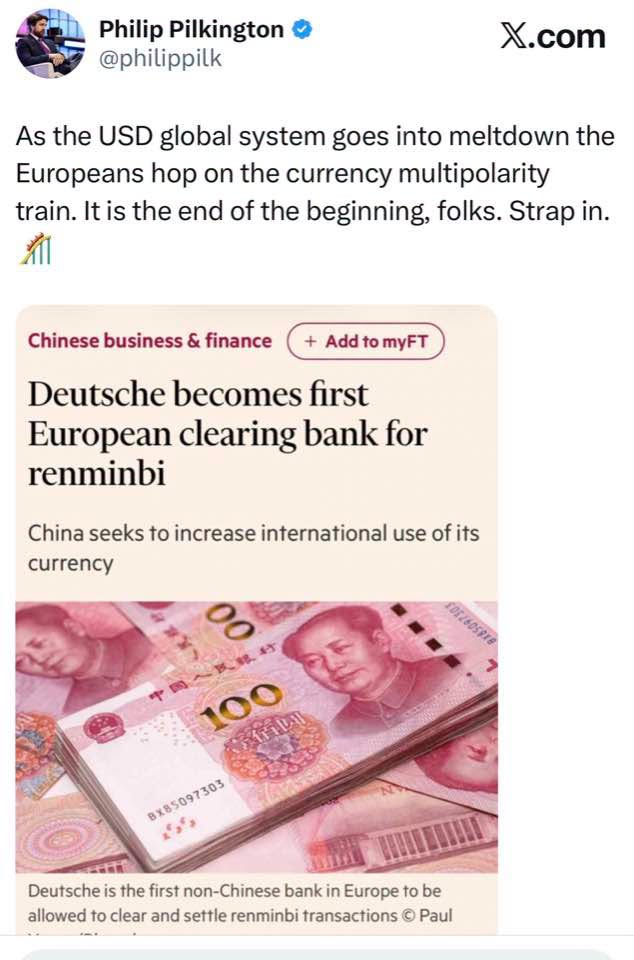
On 10 August, China’s central bank made a move that barely made headlines outside the financial press, but which deserves far greater attention. Deutsche Bank in Frankfurt was authorised as an official clearing bank for the Chinese renminbi, becoming the first non-Chinese bank in Europe to perform this function.
In practical terms, this means that European financial institutions and companies gain a more direct channel for settlement, liquidity and financing in the Chinese currency. In strategic terms, it means that the infrastructure around the renminbi is moved yet another step into the ordinary European financial system.
What matters about this development is not the share of the world’s payments the renminbi accounts for today. The dollar is still clearly dominant in international reserves, capital markets and cross-border financing. What is interesting is the change in the architecture of the system. International trade that previously went naturally via the dollar, American correspondent banks and American financial infrastructure is gaining ever more alternative channels.
This difference is fundamental. The power of a reserve currency depends not only on its market share, but on how difficult it is to avoid.
The United States has enjoyed a historically unique position because for decades the dollar has been a means of payment, a reserve asset, a commodity currency, a funding currency and a safe haven. This role has enabled Washington to exercise economic power far beyond its own borders. When banks and companies need access to the dollar system, US authorities can in practice influence transactions between parties that are neither located in the US nor trading with American companies.
This mechanism has been the basis of modern American secondary sanctions. It is also the reason China has spent considerable resources building a financial system in which a larger share of Chinese trade can be conducted without American intermediaries.
The appointment of Deutsche Bank should be understood in this context. The renminbi is moving from being a currency used mainly within Chinese or China-dominated payment flows to gaining an institutional anchor at one of Europe’s largest banks, in the financial heart of the eurozone.
The sanctions against Russia changed the calculation
The trend gathered pace after 2022.
When the US and the EU froze large parts of Russia’s central bank reserves and shut Russian banks out of Western financial infrastructure, the West simultaneously demonstrated how extensive its power over the dollar- and euro-based system actually was. The measures were intended to impose economic costs on Russia of a magnitude that would make continued warfare difficult to finance.
The result was a massive economic shock, but not the Russian economic collapse that many Western politicians expected.
Russian trade was largely redirected towards Asia, the Middle East and the Global South. Energy flows found new buyers, imports were reorganised through third countries, and domestic production was built up in areas where Western access disappeared.
Measured by purchasing-power-adjusted GDP, Russia overtook Germany as early as 2022. World Bank figures then put Russia at around 5.33 trillion international dollars, marginally ahead of Germany. Since then the gap has widened.
In nominal terms, Germany is still a much larger economy measured in market exchange rates. But for questions about how much energy, labour, industrial output and military equipment a state can mobilise within its own economy, purchasing power is a far more relevant indicator than a simple conversion into dollars.
This is not a statistical curiosity. It says something about the limits of the sanctions model. Western financial power can impose significant costs, but the effect diminishes the larger the target economy, the more raw materials it controls and the more alternative trading partners it has.
That is precisely why China represents an entirely different order of magnitude.
China is not an economy Washington can isolate without isolating parts of itself
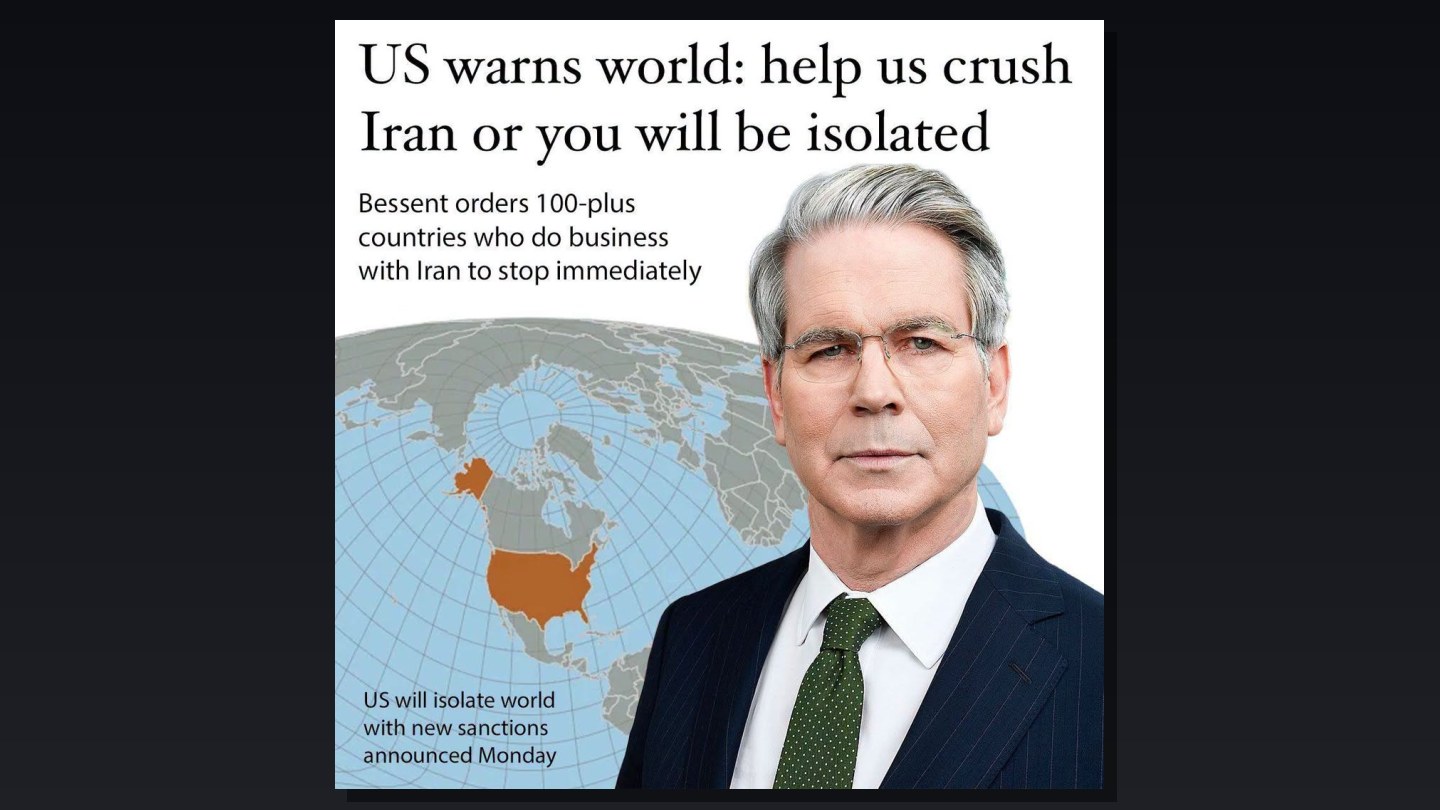
The debate in Washington about new sanctions against Chinese banks over Chinese trade with Iran exposes this contradiction particularly clearly.
China has the world’s largest industrial production base, is one of the largest trading partners for a majority of the world’s countries and controls central parts of the supply chains for electronics, batteries, solar energy, rare earths and a range of strategic inputs. The country’s four largest state banks have combined assets of around 25 trillion dollars.
Using the same financial isolation model against China as against smaller economies would therefore not be a one-sided attack on Beijing. It would be an intervention in the very infrastructure around which European, Asian and American trade is built.
Treasury Secretary Scott Bessent’s question as to why he would want to “blow up the global financial system” sums up the problem better than most strategy documents.
American sanctions have been most effective when Washington’s own cost has been low and the counterpart’s dependence on the dollar system high. This asymmetry weakens sharply when the target is China. If major Chinese banks were hit hard enough, the consequences would ripple through commodity trading, industrial financing, dollar liquidity, shipping, supply chains and Western companies’ operations in China.
At that point, financial sanctions no longer function as an instrument that can be separated from the rest of the world economy. They become a systemic weapon.
And systemic weapons carry systemic costs.
Washington’s problem is that the weapon also creates the countermeasure
The American sanctions system thus contains a built-in strategic contradiction.
The more often Washington uses the dollar system to freeze reserves, block payments and threaten third countries with secondary sanctions, the greater the economic value of the infrastructure that makes such measures more difficult.
For Russia and Iran, this is already a question of economic security. For China, it is a question of great-power strategy.
The result is not a single, coordinated “new world currency”, but a growing network of mechanisms that reduce the need for dollars in certain types of transactions.
China has built its own CIPS system for cross-border payments. Bilateral trade between China and Russia is largely conducted in national currencies. Several commodity contracts are settled without dollars. The BRICS countries are discussing greater use of local currencies and alternative payment systems. The New Development Bank gives member states a financing channel outside the traditionally Western-dominated institutions.
- In August, the governor of Iran’s central bank announced that the country expects to become a member of the New Development Bank. Iran is already a BRICS member, but NDB membership would draw the country further into this parallel financial infrastructure.
Taken individually, none of these developments changes the world’s monetary system. Taken together, they gradually reduce the extraterritorial reach that has been one of the dollar’s most important strategic properties.
The Deutsche Bank appointment is particularly interesting because it shows that this development is no longer confined to countries in conflict with Washington. The infrastructure of the Chinese currency is now being established at a central institution of the European financial system.
This is happening while America’s financial foundation is weakening
The other side of the equation is America’s own economy.
Federal government debt passed 40 trillion dollars in August. The Congressional Budget Office projects a budget deficit of around 1.9 trillion dollars in 2026, while interest costs are rising rapidly and debt held by the public is moving towards historic levels relative to GDP.
The US debt situation has no simple or immediate collapse mechanism. The US borrows in its own currency, has the world’s deepest capital market and still enjoys a demand for Treasury bonds that no other state can match.
But this privilege is directly linked to the dollar’s international role.
As long as the world’s central banks, banks, companies and investors need large amounts of dollar reserves and dollar assets, the US can finance deficits on terms that would be harder for any other state. The same reserve-currency status that gives Washington its sanctions power therefore also helps finance American government debt.
This is where the two developments meet.
Washington still needs high global demand for dollars, while American foreign policy creates ever stronger incentives to reduce this dependence.
It is a structural contradiction, not a temporary political problem.
Europe shows another side of the same strain
On the European side, meanwhile, the costs of the geopolitical confrontation are becoming far more visible.
Latvia has asked the EU for around seven billion euros linked to sharply increased defence spending and the economic consequences of the breakdown of its former ties with Russia. Riga has been among the most consistent advocates of sanctions and economic decoupling, but now argues that the burden cannot be borne nationally alone.
It is an important signal, because it illustrates how Europe’s security strategy has increasingly become a fiscal question.
Rearmament, the loss of cheap Russian energy, weak industrial growth and support for Ukraine are not isolated budget items. They compete with public investment, social policy and existing debt obligations.
Norway is in a special position economically, but the trend is visible here too. Support for Ukraine has risen from around 10.7 billion kroner in 2022 to 85 billion a year in 2025 and 2026. Norway can finance this without the kind of debt problems faced by Latvia or several other European countries, but the scale shows how quickly the economic commitment has been built up.
At the same time, Norway has a documented need for infrastructure upgrades worth several thousand billion kroner, and UNICEF has for several years recorded growing economic pressure on some Norwegian families with children.
The point is not that these items can be compared krone for krone, but that European governments increasingly have to finance existing welfare systems, a large investment backlog and a security policy that is far more expensive than it was before 2022.
The decisive shift is taking place in the infrastructure
The dollar’s dominance will not disappear because BRICS adopts a declaration or because a central bank reduces its dollar share by a few percentage points. It weakens if the economic infrastructure that has made the dollar indispensable is gradually duplicated.
This is the process China is now driving.
Beijing does not need to persuade the world’s central banks to replace dollar reserves with renminbi overnight. It is enough to ensure that Chinese trade can be financed, insured, cleared and settled without American currency when desired.
This makes Deutsche Bank’s new role far more significant than the size of today’s RMB transactions alone would suggest.
Frankfurt is not just another point on a Chinese currency map. Frankfurt is Europe’s most important financial centre, home to the European Central Bank and one of the nodes of the Western monetary system. When direct RMB clearing becomes a normal part of the infrastructure there, the Chinese currency moves one step closer to ordinary European finance.
At the same time, Washington is considering using its financial “nuclear weapon” against the country building this infrastructure.
It is hard to construct a more self-contradictory strategy.
The US is trying to preserve the dollar’s power by demonstrating how dangerous it is to depend on the dollar.
China responds by making that dependence less necessary.
Russia has already shown that a large commodity and industrial state can reorganise significant parts of its economy after being thrown out of Western financial channels. Iran is moving further into the BRICS institutions. European banks are opening direct channels to the Chinese system. Meanwhile, the American debt burden and the European costs of the current policy of confrontation are growing.
This is what makes the Deutsche Bank decision strategically important.
It is not primarily about how many renminbi are cleared in Frankfurt in 2026.
It is about the fact that the financial infrastructure of a post-dollar-dominated world is already under construction.